If you’re thinking about selling your home in Powell River this year, you’re entering a market that rewards preparation and realism. The Powell River Sunshine Coast real estate market in
Dated: January 31 2025
Views: 175

I recently had a client pay a $13,000 break fee on a 2 year old mortgage from a leading Canadian Bank. As you can imagine the client was not impressed. By factoring in an extra $13,000 penalty, the real interest rate went from 3.49% to 5.65%.
So what's the deal?
Definitions
Break Mortgage - You are cancelling your mortgage. This happens when you refinance or sell your property.
Mortgage Penalty - It's the penalty fee the bank will charge you when you cancel your mortgage before the term is up.
Mortgage Term - This is how long you are locked into your mortgage. Common mortgage terms range from 1 year to 10 years. If you break your mortgage before the term is up, you will pay a penalty.
1. What is the Bank Trying to Get Back with your Penalty?
The logic is this: If you go from a 5% rate down to a 4% rate and you have 4 years left on your mortgage, they want the interest difference that you would have paid over those 4 years. In this scenario the bank is looking for a 4% penalty fee, 1% difference for 4 years.
1a. Logical Penalty Fee Case Study
My Existing Rate = 5%
Current Market Rate = 4%
# of Years Left In Term = 4 Years
Mortgage Amount = $300,000
1b. Logical Penalty Fee Calculation
= (Rate Difference Between your Rate and Current Market Rate)*(# of Years Left in Term)*Mortgage Amount
= (My Existing Rate – Current Market Rate)*(# of Years Left in Term)*Mortgage Amount
= (5% - 4%)* 4 Years * $300,000
= $12,000 Penalty Fee
2. Real Life Case Study
Mortgage Amount - $300,000
Interest Rate - 2.89% Fixed
Term - 5 year Term
Amortization - 30 Years
Payment - $1247/month
3. Here is the Short Answer for a $300k Mortgage:
Break Mortgage After 1 Year - $7,200 Penalty
Break Mortgage After 2 Years - $13,410 Penalty
Break Mortgage After 3 Years - $13,200 Penalty
Break Mortgage After 4 Years - $6,600 Penalty
4. What is the Exact Equation Used to Calculate your Penalty?
Some banks do not use the Logical Penalty Fee calculation, instead they like to use a calculation that creates tens of thousands of dollars in extra penalty fees for every single fixed rate mortgage.
Let’s go back to the calculations:
Logical Penalty Fee = (My Existing Rate – Current Market Rate)*(# of Years Left in Term)*Mortgage Amount
4a. How do some Canadian Banks calculate Current Market Rate?
Magical Current Market Rate = Current Posted Rate - Discount
4b. What is Current Posted Rate?
The banks have two types of rates, the first is called posted rates and the second is called discounted rates. Twenty years ago when mortgage information was not readily available as it is today, posted rates were offered to the client, then as a sales strategy, the bank would say “OK since you are such a great customer and you are loyal we will give you these discounted rates”. The real discounted rates are the real market rates. As below, discounted rates are being called "special offers". Not exactly special considering every other bank is offering the same special offer....
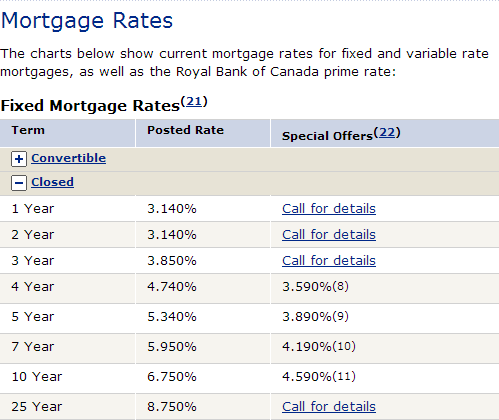
Let's assume a person has 4 years left on his mortgage and he wants to break it. We would then use the posted rate of 4.74% for this calculation
4c. How is the discount calculated?
As above, let's assume you took the special 5 year offer at 3.89%. The current posted rate was 5.34%. The discount you received off the posted rate was 5.34% - 3.89% = 1.45%.
In our case study, the client has a mortgage of 2.89%. The posted rate at that time was also 5.34%. His discount would be calculated as 5.34% - 2.89% = 2.45%.
4d. What's the difference for Logical Current Market Rate vs Magical Current Market Rate?
Current Logical Market Rate = 3.59%
Magical Current Market Rate = Posted Rate - Discount = 4.74% - 2.45% = 2.29%
Logical Current Market Rate @ 3.59%
So, imagine having a mortgage of 2.89%. The current 4 year comparable rates are at 3.59%. If we decide to break the mortgage the bank will make more money by increasing our rate to 3.59%. It's beneficial for that 2.89% to be broken.
Magical Current Market Rate @ 2.29%
What the bank is saying, is even though our comparable rate is 3.59%, we are actually going to pretend that it is 2.29%. Therefore your 2.89% mortgage is being reduced to 2.29%, you now have to pay us that interest difference that we are pretending to lose over the next 4 years.
4d. Magical Penalty Fee Exact Calculation
Magical Penalty Fee = (My Existing Rate – Current Market Rate)*(# of Years Left in Term)*Mortgage Amount
=(My Existing Rate – (Current Posted Rate - Discount))*(# of Years Left in Term)*Mortgage Amount
5. Breaking Your Mortgage After 1 Year, 4 Years Left on Term
My Existing Rate - 2.89%
Term Left on Mortgage – 4 Years
Mortgage Amount - $300,000
Current 4 Year Posted Rate – 4.74%
Discount – 2.45%
Penalty Fee = (My Existing Rate – (4 Year Posted Rate - Discount))*(# of Years Left in Term)*Mortgage Amount
= (2.89% - (4.74%-2.45%))(4Years Left)*$300,000
= (2.89% - (2.29%))(4 Years Left)*$300,000
= (.6%)*(4Years Left)*$300,000
= $7200 Penalty
Bank just made an extra $7200 on your mortgage!
5a. Real Interest Rate Paid after $7200 Penalty?
If you broke your mortgage after 1 year and had to pay a $7200 penalty, your real interest rate would not be 2.89%. You would add an extra $7200/$300,000 or 2.4%.
Real Interest Paid (estimate) = 2.89% + $7200/$300,000 = 2.89% + 2.4% = 5.29%
6. Mortgage Penalty after 2 Years, 3 years Left in Term
My Existing Rate - 2.89%
Term Left on Mortgage – 3 Years
Mortgage Amount - $300,000
Current 3 Year Posted Rate – 3.85%
Discount – 2.45%
Magical Penalty Fee = (My Existing Rate – (3 Year Posted Rate - Discount))*(# of Years Left in Term)*Mortgage Amount
= (2.89% - (3.85% - 2.45%))(3 Years Left)*$300,000
= (2.89% - (1.4%))(3 Years Left)*$300,000
= (1.49%)*(3 Years Left)*$300,000
= $13,410 Penalty
6a. Real Interest Rate Paid after $13,410 Penalty?
Real Interest Paid (estimate) = 2.89% + $13,410/$300,000/2 years = 2.89% + 2.23% = 5.12%
7. Mortgage Break after 3 Year, 2 years Left in Term
My Existing Rate - 2.89%
Term Left on Mortgage – 2 Years
Mortgage Amount - $300,000
Current 2 Year Posted Rate – 3.14%
Discount – 2.45%
Magical Penalty Fee = (My Existing Rate – (2 Year Posted Rate - Discount))*(# of Years Left in Term)*Mortgage Amount
= (2.89% - (3.14% - 2.45%))(2 Years Left)*$300,000
= (2.89% - (.69%))(2 Years Left)*$300,000
= (2.2%)*(2 Years Left)*$300,000
= $13,200 Penalty
7a. Real Interest Rate Paid after $13,200 Penalty?
Real Interest Paid (estimate) = 2.89% + $13,200/$300,000/3 years = 2.89% + 1.46% = 4.35%
8. Mortgage Break after 4 Year, 1 years Left in Term
My Existing Rate - 2.89%
Term Left on Mortgage – 1 Years
Mortgage Amount - $300,000
Current 1 Year Posted Rate – 3.14%
Discount – 2.45%
Magical Penalty Fee = (My Existing Rate – (1 Year Posted Rate - Discount))*(# of Years Left in Term)*Mortgage Amount
= (2.89% - (3.14% - 2.45%))(1 Years Left)*$300,000
= (2.89% - (.69%))(1 Years Left)*$300,000
= (2.2%)*(1 Years Left)*$300,000
= $6,600 Penalty
8a. Real Interest Rate Paid after $6,600 Penalty?
Real Interest Paid (estimate) = 2.89% + $6.600/$300,000/4 years = 2.89% + .55% = 3.44%
9. This Sounds Crazy.
I agree. Even most mortgage brokers are not aware of this. What is even worse if when you walk blindly into a bank and ask about break fees, they will have close to a zero clue how to calculate it.
Why?
If the calculation was out there, the gig would be up. If you google your banks penalty page webpage for detailed explanations of how it’s calculated, you will be blown away. They use interest rates of 6% to 9% for their case studies. I wonder why the bank doesn’t show an example with today’s current interest rates!!!!!!!!!!!!!! If they did, you would never ever get a fixed rate mortgage from that bank!
10. What’s the solution?
1. Get a smart mortgage broker
2. Don’t get fixed rate mortgages without knowing the exact calculation being used
3. Don’t walk blindly into banks
4. If your mortgage broker only talks to you about rates...run run run...
Monica has always loved Real Estate. Her late father Willy Ostensen was a very successful REALTOR® in his time and owned the brokerage before her current managing broker and brother, Ron Ostensen. ....
If you’re thinking about selling your home in Powell River this year, you’re entering a market that rewards preparation and realism. The Powell River Sunshine Coast real estate market in
Dreaming of waking up to ocean views, the sound of waves, or the quiet of a forested acreage in Powell River? The Sunshine Coast—especially the Upper Sunshine Coast around Powell River&mdash
Renting can feel like the simpler choice. You have more flexibility, fewer maintenance responsibilities, and no need to save for a large down payment right away. But long-term renting comes with
Key TakeawaysYour entryway is the first thing buyers and guests experience when viewing Powell River real estate, and it sets the tone for everything that followsThere are four common entryway:

The listing data displayed is deemed reliable but is not guaranteed accurate by CREA®. Data last updated on September 22, 2026 5:53 PM UTC The trademarks REALTOR®, REALTORS®; and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA®) and identify real estate professionals who are members of CREA®. Used under license. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned by The Canadian Real Estate Association (CREA®) and identify the quality of services provided by real estate professionals who are members of CREA®. Used under license.
Show More...